Property Development Finance
Ground-up construction loans, heavy conversions, and development exit facilities across the UK.
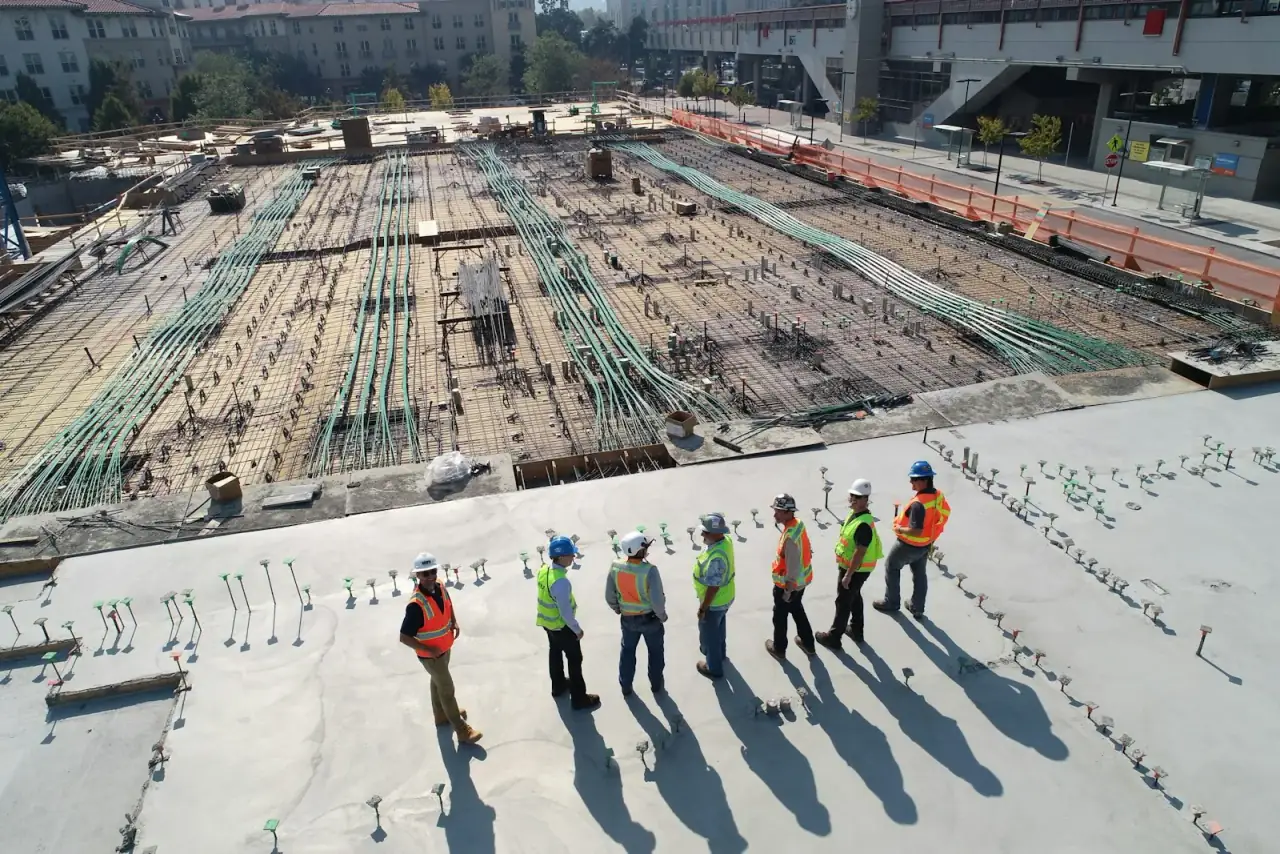
Property development finance provides staged debt facilities to fund ground-up construction, commercial-to-residential Permitted Development conversions, and major structural refurbishments across England, Scotland, and Wales.
Indicative commercial parameters aligned with Bank of England base rate environments and British Business Bank 2026 SME Finance Market standards. Final facility size, security requirements, and terms are determined solely by the underwriting criteria of the relevant third-party commercial lender. Available exclusively to active UK entities on the Companies House register.
Understanding property development finance.
Unlike standard commercial mortgages that advance a single lump sum against an existing building, development finance is structured around the project's Gross Development Value (GDV) and total build cost.
An initial advance supports the site or building purchase, followed by regular staged drawdowns released in arrears as certified by an independent monitoring surveyor throughout the construction timeline.
BusinessLending.uk is an introducer, not a lender. We do not provide personalised financial advice. Nothing on this page is advice, an offer, or an indication that finance will be available to your business.
Real businesses, real timing, real trading patterns.
Whether it fits, and how it can be built.
General indicators only. Providers set their own criteria and reach their own decisions.
This may be worth exploring if…
- You have full detailed planning consent (or clear permitted development rights) in place
- You have a quantified development appraisal with fixed-price build contracts and realistic cost contingencies
- Your team or main contractor has a proven track record of delivering schemes of comparable scale
- You have an identified exit strategy — marketing units for private sale or refinancing into commercial BTL
Common structures within the category
- 01
Senior Development Debt
The primary construction loan, typically funding up to 60%–70% of Gross Development Value (GDV) and up to 80%–85% of total project costs.
- 02
Mezzanine Development Finance
Subordinated debt that sits between the senior loan and developer equity, enabling developers to stretch overall borrowing to 90% of total costs and reduce cash equity requirements.
- 03
Development Exit Facility
A short-term bridge that replaces higher-cost construction debt once the scheme achieves practical completion, giving time to sell or let units.
Discuss your property development finance requirement.
Tell us the purpose, approximate amount and preferred timing. We will review the parameters and discuss which finance routes may be relevant.
BusinessLending.uk is a commercial finance introducer, not a lender. No upfront fees. Subject to provider assessment.
What a provider wants to understand before deciding.
- Purpose of the funding and how it supports the business
- Trading history and turnover
- Profitability and repayment capacity
- Existing borrowing and commitments
- Credit profile of the business and its directors
- Any security available, including personal guarantees
- Detailed financial appraisal showing site cost, build costs, professional fees, contingency, and Gross Development Value (GDV)
- Planning consent, approved drawings, Section 106 agreements, and building regulation approvals
- Track record and balance sheet of the main building contractor, including JCT contract terms and collateral warranties
- Independent Initial Monitoring Surveyor (IMS) report verifying project timeline and cost adequacy
Costs vary by provider, product, amount, term and the risk presented. We do not quote rates on this website because pricing is set by the provider following their own assessment. Some facilities are unsecured; others require security over an asset, a debenture, or a personal guarantee. Any costs, fees and security requirements are set out by the provider in writing before you commit.
Documents worth having to hand
Checklist- Latest filed accounts
- Recent management accounts, where available
- Three to six months of business bank statements
- A short summary of what the funding is for
- Details of existing finance agreements
- Comprehensive development appraisal and cash flow drawdown schedule
- Planning permission notice and architectural drawing plans
- Main contractor CV, insurance details, and draft construction contract (e.g. JCT Design & Build)
- Schedule of comparable local property sales supporting the projected GDV
Nothing here is mandatory before you contact us — it simply makes the first conversation more productive.
Property Development Finance — frequently asked
Straightforward answers on how property development finance works for UK limited companies, typical lender criteria, and what to prepare before enquiring.
Every business and enquiry is distinct. If you have a specific question, our team is happy to talk through your circumstances without obligation.
Discuss your funding requirementRelated finance routes
Business Loan & Debt Refinancing
Restructure existing borrowing, consolidate multiple facilities, and reduce monthly debt costs.
£25,000 – £10,000,000+12 Months to 15 Years (Depending on asset backing)Read the route
Growth & Expansion Capital
Strategic debt facilities to fund acquisitions, new premises, recruitment, and scaling operations.
£50,000 – £10,000,000+2 to 7 YearsRead the route
International Project Finance
Structured cross-border project finance and syndicated debt for UK companies and international schemes.
£1,000,000 – £50,000,000+3 to 15+ Years (Non-recourse / limited recourse project debt)Read the route
Plan for what matters most.
Explore Will Writing, Lasting Powers of Attorney and Trusts, with guidance on taking the right next step for your circumstances.
Our commercial finance introduction service is for eligible UK limited companies. Estate planning enquiries are handled separately.
 01View service
Will Writing
Explore how to document who should inherit your estate, who should act as your executors, and how your wishes should be carried out.
 02View service
Lasting Powers of Attorney
Understand how to appoint trusted people to make property and financial or health and welfare decisions on your behalf where the applicable law allows.
 03View service
Trusts
Learn about the broad purpose of trusts and why personalised legal and tax advice is needed regarding suitability, administration, responsibilities and costs.
BusinessLending.uk does not draft legal documents or provide individual legal or tax advice. We can discuss your estate-planning enquiry and, where an appropriate specialist arrangement is available, explain possible next steps. Any specialist introduction requires your agreement.
Talk through property development finance for your business.
Share the purpose, approximate amount and preferred timing. We will review the requirement and discuss possible next steps.
BusinessLending.uk is a commercial finance introducer, not a lender. No upfront fees. Subject to provider assessment.