Skip to content
BusinessLending.uk logo
Case studies

How the right funding structure can support a business plan.

Real-world-style examples showing how appropriate funding structures can help businesses manage cash flow, fulfil contracts, invest in equipment and complete property projects.

Important: These case studies are provided for information only. Finance terms, pricing, eligibility and outcomes vary by lender, borrower circumstances and market conditions. Illustrative figures are not guarantees of approval or future performance.
01

£50,000 Working Capital Facility for a Kitchen Supplier

Executive summary

BorrowerKitchen Company A, an expanding joinery and kitchen supplier
Funding request£50,000 short-term working capital loan
ProjectSupply and install 100 high-specification kitchens for a local residential property developer
Fulfilment periodFour months
Contract value£350,000
Illustrative structureSubject to independent lender underwriting

The opportunity

Developer Company B was delivering a new 100-unit apartment complex. The developer had a solid credit rating and a proven record of completing four previous developments. Kitchen Company A secured a business-to-business contract to supply and install 100 flat-pack kitchen units with quartz worktops.

Contract payment structure

30% deposit upfront£105,000
40% midpoint and delivery payment£140,000
30% final sign-off payment£105,000
Total contract revenue£350,000

The cash-flow gap

Although the contract was profitable, the business faced a temporary working capital shortfall because major material and labour costs had to be paid before the first milestone payment fully covered the initial outlay.

Bulk raw materials: cabinets, doors and hardware£110,000
Quartz worktop fabrication deposit£25,000
Labour and logistics£20,000
Total initial outflow£155,000

£155,000 initial outflow − £105,000 deposit = £50,000 temporary cash deficit during Weeks 3 to 6.

Financial position

Gross profit margin32%
Gross profit£112,000
Net profit margin18%
Net profit before finance cost£63,000
Loan as a percentage of contract revenue14%
Illustrative four-month interest (£50,000 at 10% per annum)£1,666.67

The planned repayment source was the £140,000 midpoint payment due in Month 3.

Risks and mitigations

  • Developer payment delays: The contract included late-payment penalty clauses. Kitchen Company A retained title to the goods until installation and payment, and the developer’s previous payment history was reviewed.
  • Supply-chain disruption: Materials were sourced from two independent European suppliers rather than relying on a single vendor.
  • Installation cost overruns: A separate 10% contingency reserve of £12,000 was included in the company’s internal budget outside the borrowed amount.

Finance structure and outcome

In this illustrative scenario, the facility is structured as a four-month unsecured business loan of £50,000, with bullet repayment planned for Month 3, supported by a director personal guarantee and an assignment of contract receivables. Based on £63,000 net profit before finance costs less £1,666.67 illustrative interest, the modelled net project profit is £61,333.33 after interest (before any applicable lender arrangement fees).

Figures are illustrative unless expressly stated otherwise and do not constitute an offer, quotation, recommendation, or guarantee of finance. Rates, fees, eligibility, and outcomes depend on provider assessment and individual circumstances.

Discuss Working Capital FinanceExplore route guide

BusinessLending.uk is a commercial finance introducer, not a lender. We do not make lending decisions or provide personalised financial advice. Finance is subject to lender assessment, eligibility criteria, terms and conditions.
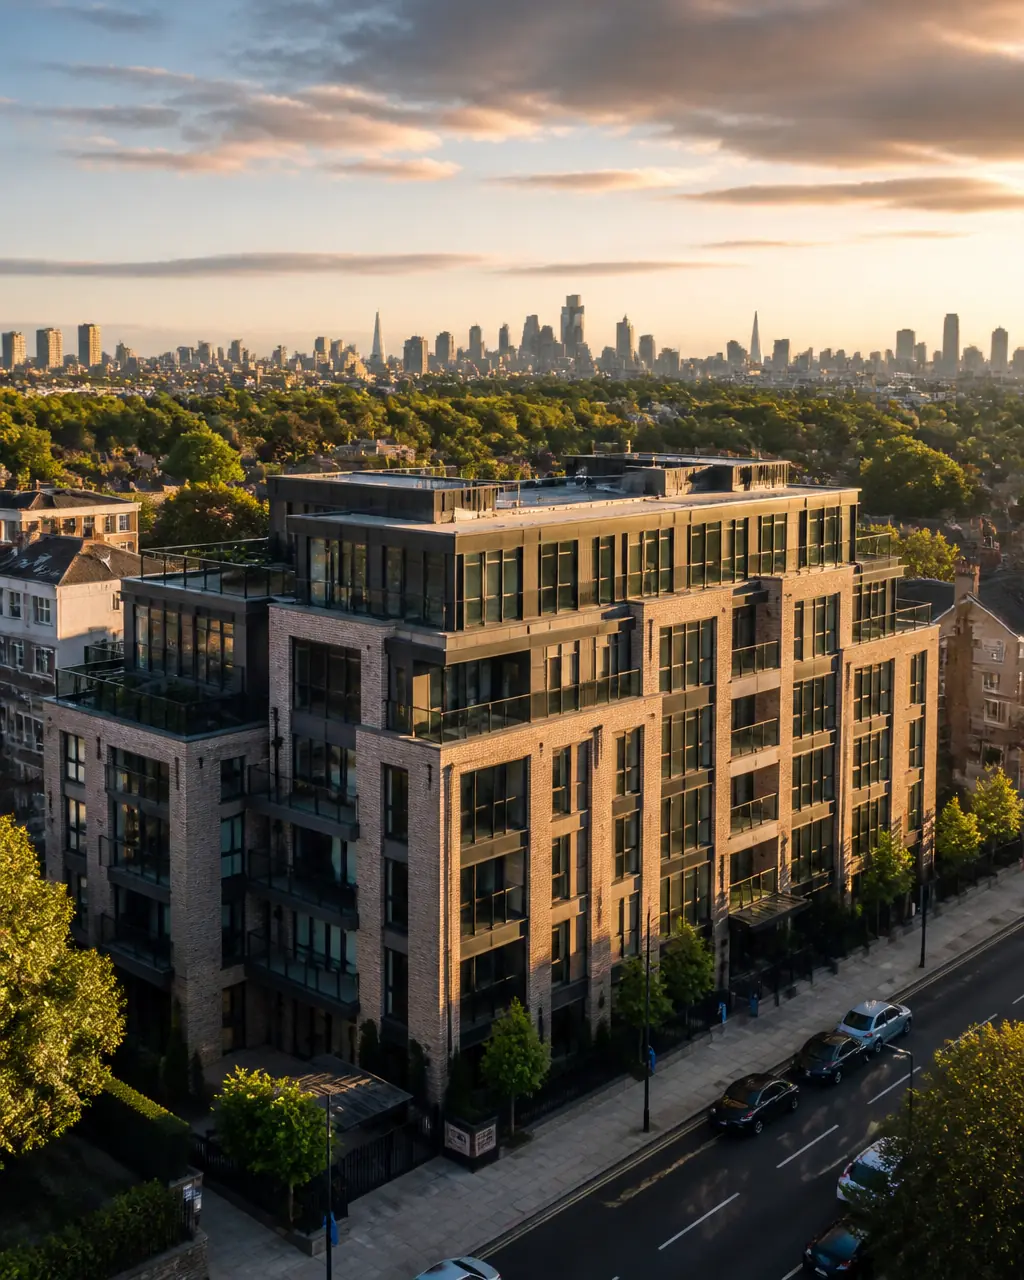
A joinery professional fitting a high-end kitchen worktop
02

£3.5 Million Bridging Facility for a 30-Apartment Development

Project overview

This illustrative example shows how a bridging finance facility could support the acquisition and refurbishment of a 30-apartment residential development.

Property purchase

Purchase price£5,000,000
Bridging loan at 70% LTV£3,500,000
Developer contribution£1,500,000

Development costs

Refurbishment costs£1,500,000
Total project cost£6,500,000

Illustrative bridging finance costs

Loan amount£3,500,000
Interest rate0.80% per month
Loan term12 months
Monthly interest£28,000
Total interest over 12 months£336,000
Arrangement fee at 2%£70,000
Exit fee£0, illustrative
Estimated legal and valuation costs£25,000
Total finance costs£431,000

Sale of completed apartments

Gross development value£9,000,000
Less bridging loan repayment£3,500,000
Less interest£336,000
Less arrangement fee£70,000
Less legal and valuation costs£25,000
Less refurbishment costs£1,500,000
Less initial equity contribution£1,500,000
Illustrative net profit£2,069,000

The figures above are illustrative. Actual bridging rates, fees, terms, valuations, exit requirements and lender criteria will vary. For schemes requiring staged construction drawdowns rather than acquisition bridging, explore property development finance, or review our guide on what lenders look at for development finance.

Figures are illustrative unless expressly stated otherwise and do not constitute an offer, quotation, recommendation, or guarantee of finance. Rates, fees, eligibility, and outcomes depend on provider assessment and individual circumstances.

Discuss Bridging FinanceExplore route guide

BusinessLending.uk is a commercial finance introducer, not a lender. We do not make lending decisions or provide personalised financial advice. Finance is subject to lender assessment, eligibility criteria, terms and conditions.
A modern residential apartment development in London
03

Invoice Finance for a Growing Wholesale Distributor

The challenge

A wholesale distribution company secured several new contracts but experienced cash-flow pressure because customers were taking between 60 and 90 days to settle invoices. Although the company remained profitable, delayed customer payments contributed to supplier arrears and created pressure around payroll and the purchase of additional stock required for new orders.

Business position

Outstanding sales ledger£500,000
Trade creditors£180,000
HMRC payment arrangement£70,000
Monthly payroll£90,000
Customer payment terms60–90 days

Invoice finance solution

The business secured an invoice finance facility providing an advance of 85% of approved invoices within 24 hours.

Outstanding invoices£500,000
Advance rate85%
Initial funding available£425,000

How the funding supported the business

  • Pay suppliers and begin restoring key trading relationships.
  • Meet payroll commitments on time.
  • Reduce outstanding trade arrears.
  • Continue purchasing stock needed to fulfil new customer orders.
  • Improve working capital while waiting for customers to settle invoices.

The facility helped the business convert unpaid invoices into usable working capital without waiting 60 to 90 days for customer payment. To understand how receivables financing compares to traditional bank overdrafts, read our comparison on invoice finance vs overdraft.

Figures are illustrative unless expressly stated otherwise and do not constitute an offer, quotation, recommendation, or guarantee of finance. Rates, fees, eligibility, and outcomes depend on provider assessment and individual circumstances.

Discuss Invoice FinanceExplore route guide

BusinessLending.uk is a commercial finance introducer, not a lender. We do not make lending decisions or provide personalised financial advice. Finance is subject to lender assessment, eligibility criteria, terms and conditions.
A warehouse manager checking inventory on a tablet
04

£225,000 Asset Finance Facility for New Manufacturing Equipment

The opportunity

A growing manufacturing company secured several new contracts and needed additional machinery to increase production capacity. Rather than using a significant portion of its working capital to purchase the equipment outright, the business chose an asset finance structure that spread the cost over five years.

Equipment purchase

CNC manufacturing machine£250,000
Deposit at 10%£25,000
Asset finance facility£225,000
Finance term60 months

Illustrative repayment

Asset finance amount£225,000
Monthly repaymentApproximately £4,650*
Finance term60 months

*Illustrative only. Actual repayments depend on the lender, interest rate, fees and finance structure.

Benefits to the business

  • Acquire essential machinery without a large upfront cash payment.
  • Preserve working capital for day-to-day operating expenses.
  • Increase production capacity to fulfil new customer orders.
  • Spread the cost through manageable monthly repayments.
  • Generate revenue from the asset while paying for it over time.

Business outcome

The new machinery increased production by approximately 35%, helping the company secure additional contracts and improve operational efficiency. Instead of committing £250,000 to a single purchase, the company retained capital for recruitment, raw materials and future growth.

Assets that may be suitable for finance

Asset finance may be available for a wide range of business equipment, including commercial vehicles and HGVs, construction and agricultural machinery, manufacturing and engineering equipment, printing and packaging equipment, medical and laboratory equipment, IT hardware and technology, catering and hospitality equipment, and renewable energy systems.

Is asset finance suitable for your business?

Asset and equipment finance can help a business acquire essential equipment while preserving working capital and spreading the cost over an agreed period. Availability and structure depend on the asset, the business’s financial position and the lender’s assessment.

Figures are illustrative unless expressly stated otherwise and do not constitute an offer, quotation, recommendation, or guarantee of finance. Rates, fees, eligibility, and outcomes depend on provider assessment and individual circumstances.

Discuss Asset FinanceExplore route guide

BusinessLending.uk is a commercial finance introducer, not a lender. We do not make lending decisions or provide personalised financial advice. Finance is subject to lender assessment, eligibility criteria, terms and conditions.
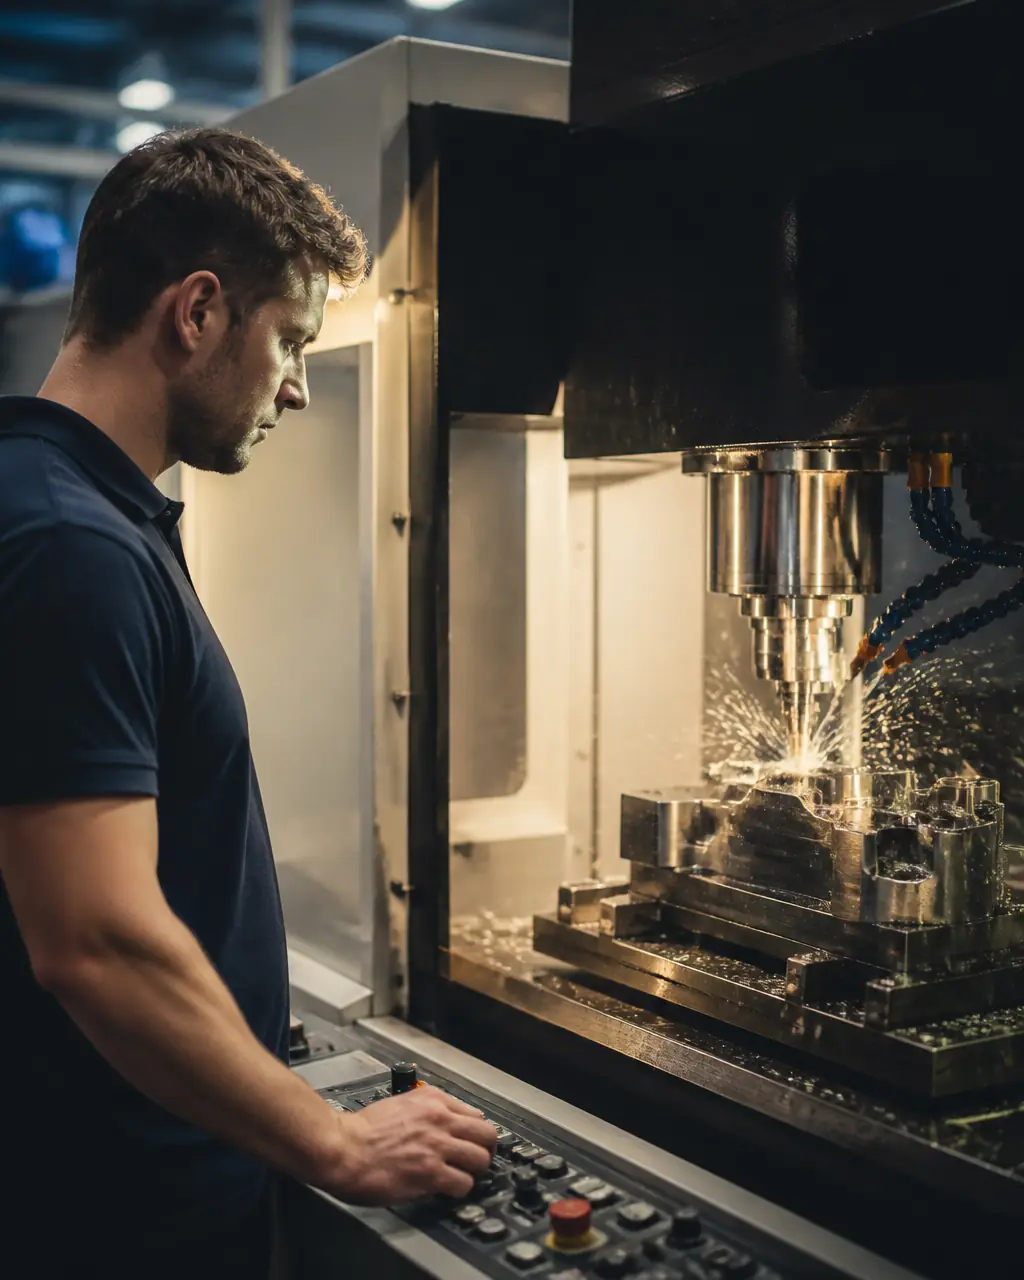
An engineer operating a CNC machine in a manufacturing facility
Representative Scenarios

Commercial Structuring Scenarios & Underwriting Frameworks

Representative examples showing how UK limited companies across distinct sectors align facility structures, security requirements, and cash-flow horizons with commercial lending criteria.

Scenario 01£240,000 • 60 Months

Midlands Precision Engineering Ltd

Precision Engineering & Aerospace Manufacturing
Requirement / Challenge
Acquiring two 5-axis CNC machining centres (£240,000) without depleting cash reserves ahead of a major aerospace contract delivery.
Structure Introduced
Hire Purchase (HP) over 60 months with a 10% deposit + VAT deferral structure.
Key Underwriting Factors
5 years filed accounts at Companies House, supplier pro-forma invoice, strong secondary resale value of machinery, healthy forward order book.
Scenario 02£350,000 • Rolling Facility

North West B2B Wholesale Distributor Ltd

Food & Beverage Distribution
Requirement / Challenge
Bridging a 60-day payment gap between container import payments and major supermarket debtor receipts (£350,000 facility).
Structure Introduced
Confidential Invoice Discounting releasing 85% of verified B2B invoice value within 24 hours.
Key Underwriting Factors
Quality of debtor book, aged receivables ledger, clean credit control processes, diversified commercial client base.
Scenario 03£680,000 • 12 Months

South East Commercial Property SPV Ltd

Commercial Property Investment & Development
Requirement / Challenge
Completing an auction purchase on a mixed-use commercial unit (£680,000) within a 28-day statutory completion window.
Structure Introduced
12-Month Commercial Bridging Loan at 65% LTV, exited via long-term Commercial Mortgage once tenant lease renewed.
Key Underwriting Factors
First legal charge over property, clear exit strategy via refinance, strong director property track record.

Figures are illustrative unless expressly stated otherwise and do not constitute an offer, quotation, recommendation, or guarantee of finance. Rates, fees, eligibility, and outcomes depend on provider assessment and individual circumstances.

Structuring & Criteria

Frequently asked about case studies & facility structuring

Clear, straightforward answers regarding our commercial finance introduction process, eligibility criteria, and how enquiries are handled.

Every business and enquiry is distinct. If you have a specific question, our team is happy to talk through your circumstances without obligation.

Discuss your funding requirement

Yes. These scenarios illustrate how commercial lenders evaluate risk, calculate loan-to-value (LTV) limits, and structure repayment mechanisms. However, actual pricing and terms depend on your company's trading history, financials, and security. Review our how it works guide to see the underwriting sequence.

ESTATE PLANNING

Plan for what matters most.

Explore Will Writing, Lasting Powers of Attorney and Trusts, with guidance on taking the right next step for your circumstances.

Our commercial finance introduction service is for eligible UK limited companies. Estate planning enquiries are handled separately.

Find the right funding structure for your business

Every business and project is different. We help business owners understand the available options and introduce suitable enquiries to lenders and specialist finance providers across our network.